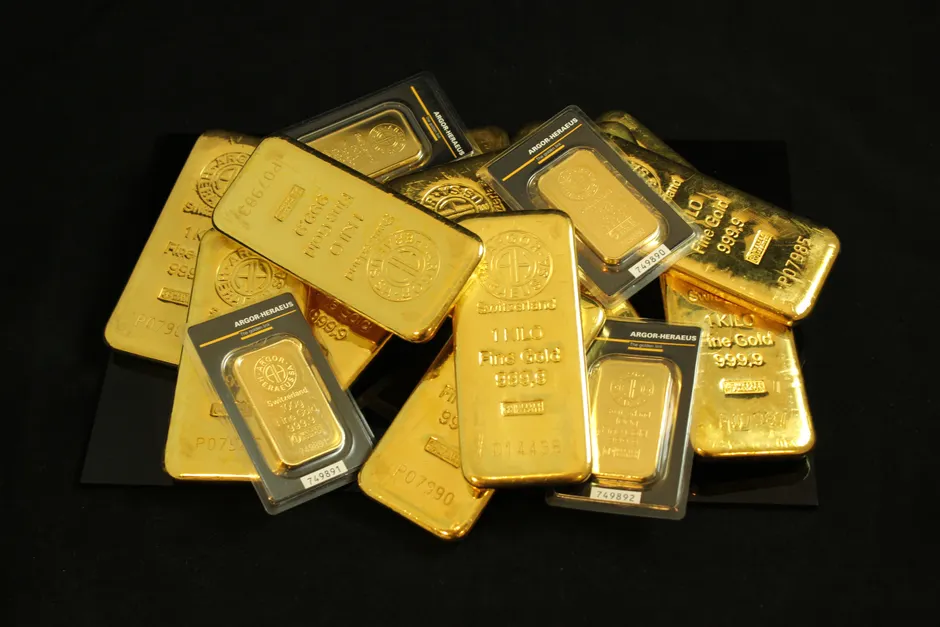
Gold Fades as Oil and Front-End Yields Reprice the Policy Path

Front-month gold futures slipped 0.4% to $4,291.60 per troy ounce.
The print capped a run of softer fixings in early September. U.S. gold futures dropped 2.2% to $4,311.20 to a more than one-month low on Sept. 14, as sharply higher crude oil prices were driving inflation expectations higher. On Sept. 8, spot gold fell 0.4% to $4,385.09 per ounce, while U.S. gold futures for December delivery dropped 1% to settle at $4,430.10. Reuters
Rates repricing
The rates leg moved first. On Aug. 28, the 2-year Treasury yield rose 0.118 percentage point to 4.348%, its biggest one-day rise since March. Wall Street Journal
That is 11.8 basis points in a session. For a front-end tenor, that is a material repricing of the near-term policy path.
On Sept. 3, stocks rallied after Fed Governor Christopher Waller said he would back holding interest rates steady if August inflation data supports it. Wall Street Journal
The sequence matters. Yields jumped. Equities then stabilized on a conditional hold signal tied explicitly to incoming inflation data. Gold faded as nominal yields rose and oil complicated the inflation outlook.
A separate Wall Street Journal report, dated unknown, said gold futures settled down 9.5% to $4,570.40 a troy ounce for the week, a $482.10 loss described as the largest single-week dollar decline on record. That level sits above the September dated fixings. Treat it as context for the scale of weekly dollar volatility, not as the current price. The dated September sequence is lower.
From record run to liquidation
On June 23, gold fell below $4,000 an ounce for the first time since November. Bloomberg reported bullion prices dropped as much as 3.8% to trade below $3,960 an ounce. Bloomberg
The June break followed a long advance. In a Sept. 23, 2025 Trading Day report, gold hit a new high of $3,790 per ounce. In the same report, platinum rose 4% to a new 11-year high, and oil was up around 2% on supply issues. Silver rose above $45 an ounce for the first time since 2011, a 14-year high.
The 2024 base was far lower. On Sept. 12, 2024, spot gold was up 1.7% at $2,554.05 per ounce as of 02:10 p.m. ET. U.S. gold futures settled 1.5% higher at $2,580.60 that day. In a Sept. 17, 2025 report, gold prices fell nearly 1% on Wednesday after scaling a record high earlier in the session.
The broader context here is a familiar cross-asset tightening of financial conditions. Higher crude lifts headline inflation and breakevens. Front-end nominals rise. Real yields firm unless inflation compensation rises faster. Non-yielding bullion and long-duration risk both feel it.
In my view, the desk-level question is what portion of the gold pullback is rates discounting versus forced de-risking. The June episode was framed around liquidation during a tech-led selloff. The September move lines up more cleanly with oil-led inflation repricing and the 2-year spike. That distinction affects carry, margin, and how futures basis and options skew behave around the data.
Looking at what this means for positioning, conditional guidance is the binding constraint. A hold backed only if August inflation data supports it keeps every energy print relevant to policy pricing. Oil up 2% on supply issues is not the same shock as a sustained crude rally feeding expectations, but futures traders price the risk before it settles. Gold, silver and platinum can diverge in that window because industrial beta and inventory dynamics differ from monetary demand.
The price history reinforces the point. From $2,554.05 spot in September 2024 to $3,790 in September 2025 to prints above $4,500 and then back below $4,000 in June and toward $4,291.60 by Sept. 15, the range has widened. Dollar losses per week can set records even when percentage moves look contained. That is arithmetic at higher nominal levels, but it changes variation margin calls and stop discipline.
For borrowers and savers, the transmission is indirect. Front-end yields set the anchor for money-market returns and short-term funding. A conditional pause does not lock in the curve. It leaves it data dependent. For investors watching metals as a hedge, the recent tape is a reminder that inflation upside does not automatically support bullion if it also lifts the discount rate applied to all long-duration exposures.