S&P 500 Takes 28th Record of 2026 as Breadth Splits Beneath Highs
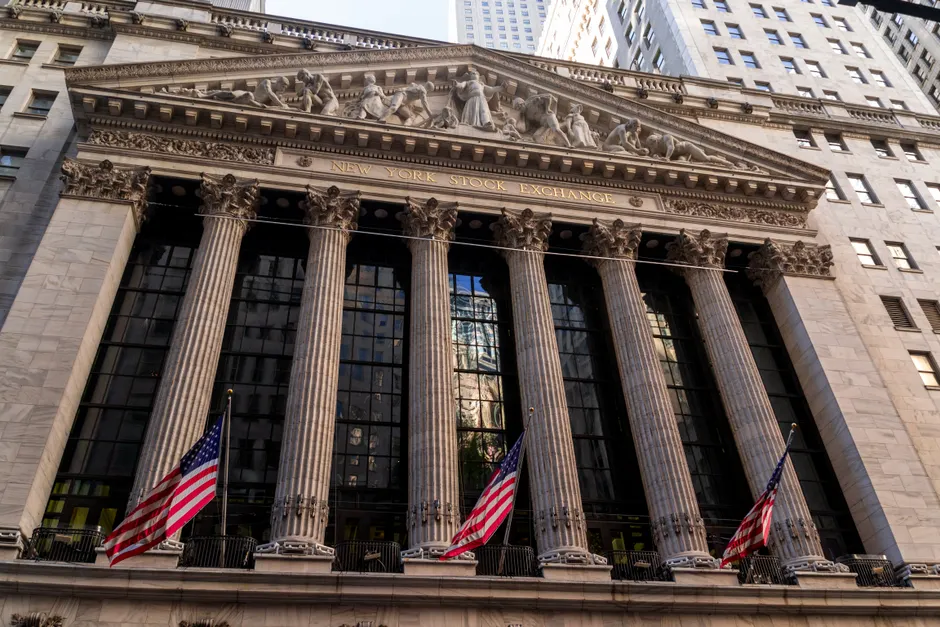
Two of the three major U.S. stock benchmarks closed at record highs on October 6, 2026.
The S&P 500 gained 44.98 points, or 0.58%, to finish at 7818.93, its 28th record close of 2026. The round-number read on the session was a 0.6% advance to 7819. Wall Street Journal Wall Street Journal
The Nasdaq Composite added 122.48 points in the same session. MarketWatch Breadth under the index moves was uneven. The S&P 500 posted 23 new 52-week highs against 2 new lows. The Nasdaq Composite recorded 61 new highs and 182 new lows. Reuters
October 6 capped a sequence of record prints. On October 5, U.S. stocks climbed with the S&P 500 hitting a record high, while the Nasdaq was on track for a second consecutive record. Wall Street Journal That followed October 4, when the Nasdaq hit a record as the dollar and Treasury yields climbed and oil prices eased. Reuters
The start of the month was firmer but less euphoric. On October 1, stocks inched higher to start October trading, while oil prices rose. The 10-year Treasury yield retreated from a 24-year high that day.
Those cross-asset pulls have been in place for months. On July 22, Treasury yields continued to tick higher alongside oil prices, with the 10-year yield close to its 2026 high point. The equity advance has compounded through that rate backup. The S&P 500 closed above 7,000 for the first time earlier in the year, and the Nasdaq closed up 2.3% at 27122.09 for its highest close on record as reported in September 21 coverage.
The broader context here is concentration versus participation. A 28th record close with only 23 new 52-week highs and 2 new lows on the S&P 500 points to cap-weighted leadership doing the work. The Nasdaq skew is starker. Sixty-one new highs alongside 182 new lows on a day the Composite advanced more than 100 points is a classic late-stage breadth divergence, where index-level momentum coexists with a long tail of constituents making fresh lows.
Looking at what this means for positioning, the tape rewards precision on exposure. Index beta, single-stock dispersion and rates sensitivity are no longer substitutes for each other. When records arrive with rising long-end yields, a firm dollar and firm-to-rising oil, duration risk and input-cost pressure sit inside the multiple. For active books, that mix puts a premium on balance-sheet quality, pricing power and hedge calibration, because headline index strength can mask fragile breadth underneath.


