The Fed Hiked Rates — What It Means for Your Savings and Loans
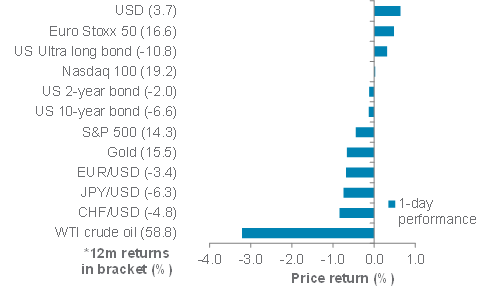
On 25 September 2026, Standard Chartered published its Global Market Outlook called "Earnings above all." It closed a month when its regional notes focused on a rate hike by the Federal Reserve, the US central bank, and the market reaction after. Global Market Outlook
On 17 September, its Brunei Market Watch was called "Fed builds credibility with hike; one more likely in Dec". On 18 September, its Singapore outlook was called "A Fed credibility – induced bounce". Brunei Market Watch Singapore Market Outlook
The 17 September note gave the key number. The yield on the US 2-year government bond, the interest the government pays to borrow for two years, rose 7 basis points to 4.74%, the bank said. A basis point is 0.01 points. Markets priced three more 25-basis-point hikes, or 0.25-point moves, by June 2027. The bank expected one more hike in December.
The 18 September note called the Fed move a moderately hawkish pivot that helped repair its record on fighting rising prices. It said the Bank of Japan raised rates in the same week as the Fed move covered in that Weekly Market View.
That hike was not seen as certain beforehand. In its Weekly Market View on 11 September 2026, Standard Chartered noted residual risk the Fed could hold back the next week, possibly due to pressure from the Trump administration. Kenya Weekly Market View Earlier bank commentary had said US long-end yields had been pushed to cycle highs by rising term premia and fiscal strain.
After the repricing, the bank changed its view on duration. In its Weekly Market View on 2 October 2026, Standard Chartered said the recent bond sell-off had created a compelling opportunity for investors with a 6-12-month horizon. It noted the long end had already sold off.
The broader context here is a two-part rates story. Think of it like renting for months versus for years. The front end repriced on near-term policy guesses, with three extra 25-basis-point moves priced through June 2027. The long end was described separately, with cycle highs tied to term premia and fiscal strain rather than the Fed decision alone. That split matters for curve positioning and for separating what was known from what was priced.
In my view, the credibility talk needs questioning. A moderately hawkish pivot can steady short-term guesses without fixing duration supply or budget questions at the long end. For a 6 to 12 month horizon, much turns on whether term premia shrink, whether those priced hikes happen, and whether company earnings can support markets if rates stay high. The December call and June 2027 pricing give a clear test. If those hikes do not arrive, the 4.74% print will look like an overshoot. If they do, the bond sell-off case will need earnings strength to offset the drag from higher discount rates.