Lucid, Bolt Plan 25,000 Robotaxis for Europe

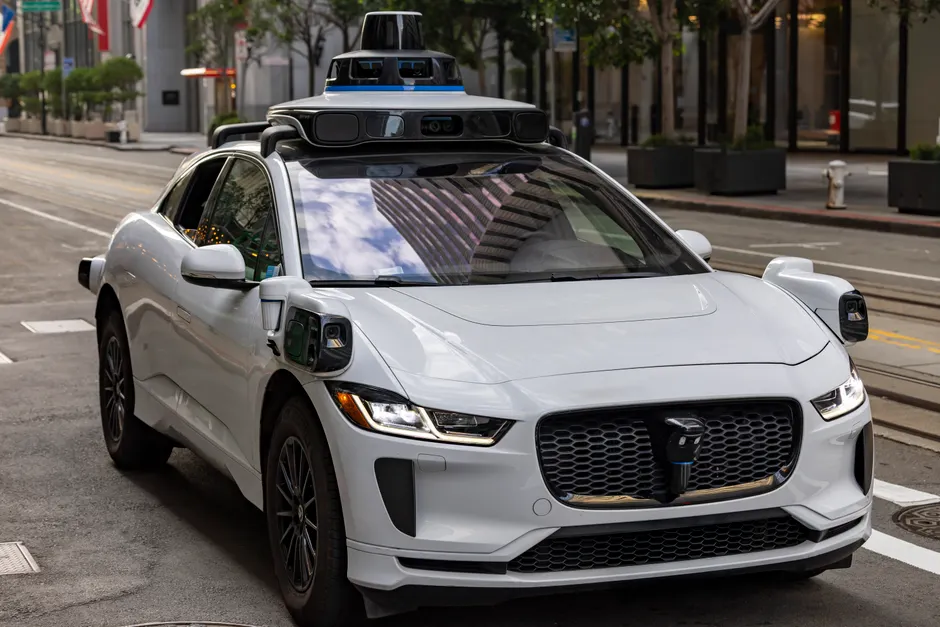
Lucid and Bolt are partnering to develop autonomous vehicles for deployment in Europe. Engadget Bolt plans to deploy at least 25,000 fully autonomous Lucid vehicles in major European cities. Reuters
Bolt is identified as an Estonian car-sharing platform. U.S. News Bolt plans to own and operate the Lucid fleet itself. The company places that commitment inside a wider target of 100,000 autonomous vehicles on its platform by 2035.
Bolt has not revealed when the Lucid-based robotaxis are likely to go into service. Reuters reported the 25,000-vehicle plan on September 17, 2026.
The vehicle is being designed for Level 4 automation, meaning autonomous operation within defined boundaries. It will be based on Lucid's midsize platform and will likely use NVIDIA's Hyperion autonomous vehicle architecture. Engadget Lucid previously showed a two-seater robotaxi prototype based on that midsize platform.
That platform remains pre-volume. Lucid delayed its Cosmos SUV, its first EV based on the midsize platform, to early 2027. Lucid also laid off around 18 percent of its workforce.
Lucid has a separate robotaxi partnership in the United States with Uber and Nuro. Under that arrangement, Uber plans to deploy 35,000 Lucid robotaxis in the US. Nuro has started testing the Lucid Gravity robotaxi with a safety driver in Houston and the San Francisco Bay Area.
The broader context here is platform leverage and operator structure. Lucid is trying to spread one midsize architecture across a consumer SUV, a two-seater robotaxi concept, a US program built around Uber and Nuro and the Gravity, and now a European program with Bolt. That spreads engineering cost across more variants. It also links the programs together. A delay to the base vehicle, as with Cosmos to early 2027, affects timing confidence for autonomy derivatives even when the autonomy stack comes from partners.
Looking at what this means for deployment, ownership matters. Bolt owning and operating removes resale from the equation and puts utilization, charging, cleaning, servicing and availability on a single fleet operator. In my view, that is the more workable structure for Level 4 services in defined urban areas, where daily uptime and operational discipline decide unit economics. No service date was given. That absence is material. Fleet counts at this stage are procurement intent, not deployed capacity.
The scale under discussion is not a pilot. Twenty-five thousand vehicles implies depot capacity, parts supply, maintenance staffing and city-by-city approval. Bolt's 2035 target of 100,000 autonomous vehicles frames the Lucid allocation as an initial tranche rather than a ceiling. Testing precedents are still at the safety-driver stage in the US program, which indicates how much validation remains before driverless operation at volume.
In my view, the encouraging element is reuse across geographies and operators. If the same midsize platform and Hyperion architecture can support US operation with Uber and Nuro and European operation with Bolt, development cost spreads across more vehicles and more miles. That is how automated transport gets cheaper to build and to run. The work ahead is integration and validation inside defined boundaries, not invention of another vehicle.