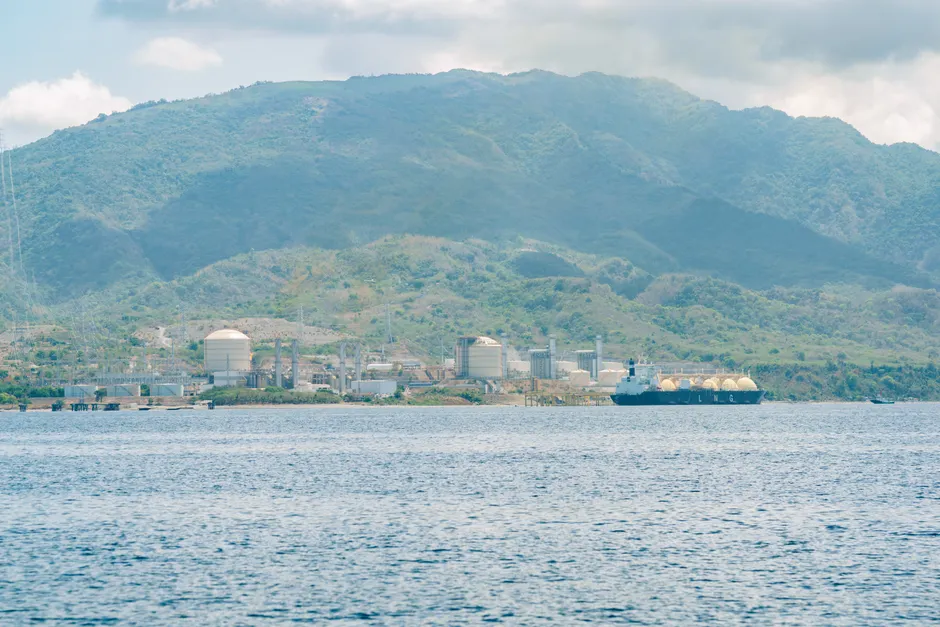
US Gas Drops 3% on Demand Cut as Appalachian Spot Hits 2020 Low
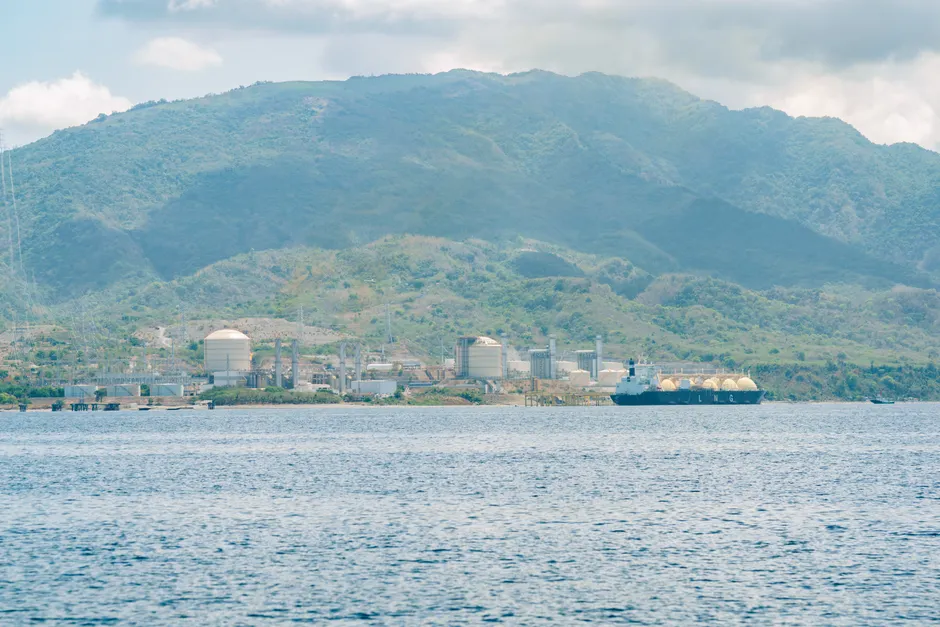
U.S. natural gas futures fell about 3% on Oct. 12 on a lower demand forecast, with Pennsylvania spot prices dropping to their lowest since November 2020. Pipeline & Gas Journal
The pullback reversed a firm tone from the prior week. The November contract had risen 1.6% to $3.22/mmBtu on Oct. 9, ending that week up 6.1% after recovering the previous session's losses. Wall Street Journal
CME Group prints on Oct. 16 put Henry Hub futures at a last price of 3.192, down 0.044 or 1.36%, on volume of 12,797. CME Group The prior session print on Oct. 15 was 3.212, down 0.024 or 0.74%, on volume of 479. CME Group A separate calendar-page quote at 07:30:50 AM CT on Oct. 16 showed 3.122, down 0.114 or 3.52%, on volume of 37,120. CME lists the product under Globex code NGX26 and reported estimated total volume of 698,355 for Henry Hub settlements. A delayed front-month quote (NGc1) stood at $3.26 on Oct. 15, up $0.06 or 1.84%. Reuters
The weakness was concentrated in physical Appalachian basis. Pennsylvania spot at lows not seen since November 2020 points to regional takeaway or demand constraints rather than a uniform Henry Hub repricing. That is consistent with the demand-led explanation for the futures move.
Power burn and LNG feedgas have both been soft points for the curve. Futures started the week of Sept. 8 lower as cooler late-September weather was expected to cut power-sector demand. Wall Street Journal Earlier in the injection season, futures eased as daily flows to LNG export plants fell to a four-month low. Reuters
Storage remains ample into the shoulder season. The EIA forecast inventories to build by 328 Bcf during October to reach 3,850 Bcf at the end of October 2026. EIA A build of that size leaves the market carrying a comfortable cushion into winter, muting the effect of short-term weather revisions on the front of the curve.
The U.S. softness contrasts with Europe. European benchmark gas prices jumped more than 150% in 2026, with reserves at lows. Reuters
The broader context here is a split market. U.S. futures near $3.20 with Appalachian spot deeply depressed and storage headed toward 3,850 Bcf describe a market pricing near-term deliverability and injection capacity, not winter scarcity. Europe pricing more than 150% higher on the year describes the opposite: low inventories bidding for marginal molecules. For U.S. traders, the variables to watch are the pace of October injections against that 328 Bcf forecast, any recovery in LNG feedgas from the June four-month low pattern, and whether weak Appalachian cash begins to drag Henry Hub or remains a basis story. Volatility around the November contract roll fits that tension, with a 6.1% weekly gain followed by a 3% demand-driven drop in successive sessions.