A Thousand Years of IOUs — and the 1648 Bond Still Paying
Robin Wigglesworth, the Financial Times' Global Finance Correspondent, is the author of A Fabulous Debt: The Epic Story of How Bonds Built the Modern World, a thousand-year look at bonds. The book is Wigglesworth's follow-up to Trillions, his history of index funds. Fortune Penguin Random House
The U.S. edition is listed by Portfolio with ISBN 978-0-593-71918-3 and a cover price of $35. Publishers Weekly Penguin Australia lists the book as a 416-page Trade Paperback from imprint Penguin General UK, with ISBN 9780241705681 and a publication date of 5 January 2027. Penguin Australia
What that publishing detail tells us is the U.S. and U.K./Australia releases have separate structures. Portfolio handles the U.S. edition. Penguin General UK is the listed imprint for the Australian edition. At 416 pages in trade format, it is a full-length book for general readers, not a condensed market primer.
For context on method, his last book is a useful guide. Trillions reconstructed the index-fund industry through personalities, product design and cost compression, or steadily falling fees. A thousand-year bond history points to a similar archive-based approach, this time applied to credit contracts, or loan deals, plus borrowers and intermediaries.
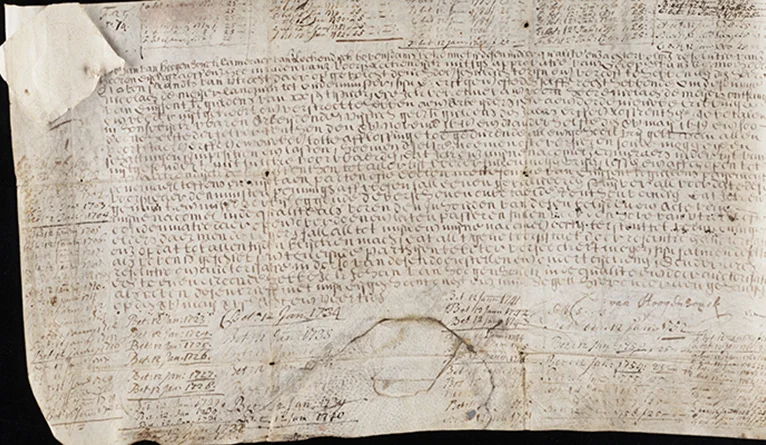
The long end of that history is still live. Yale University owns a Dutch water bond issued in 1648 that still pays interest. Yale News The instrument is a perpetual bond, a bond with no maturity date that pays interest indefinitely rather than repaying principal on a set day. It was issued to finance improvements to a local dike system. The issuer was the Hoogheemraadschap Lekdijk water board. Yale Alumni Magazine
A perpetual removes maturity. That leaves everything else. Credit, or whether the borrower keeps paying, plus currency, law and inflation do the work over centuries. Inflation matters because it shrinks what each interest payment can buy.
The broader context here is why a thousand-year frame helps people who live in quarters. Bond math squeezes a lot of future time into one price today. A perpetual makes that squeeze explicit. With no principal repayment date, value rests entirely on whether the interest payments, the coupon, keep coming and whether the legal borrower survives in some form. That a 1648 water-board obligation now sits in a modern university collection puts the spotlight on documentation, succession and servicing, the unglamorous plumbing that decides whether a contract outlives its original issuer.
In my view, the practical payoff is not nostalgia. It is calibration. Many models of default, recovery and term premia, the extra yield for holding longer bonds, lean on data since World War II. A longer record includes more political and monetary regimes a bond contract has had to survive. That does not rewrite pricing models directly. It disciplines the assumptions fed into them, especially about what counts as a rare restructuring, currency change or legal break. For a market built on promises about the future, the age of the oldest promise still being kept matters.


