Lula Wins a Fourth Term as Brazilian Assets Slide, While U.S. Markets Stay Calm
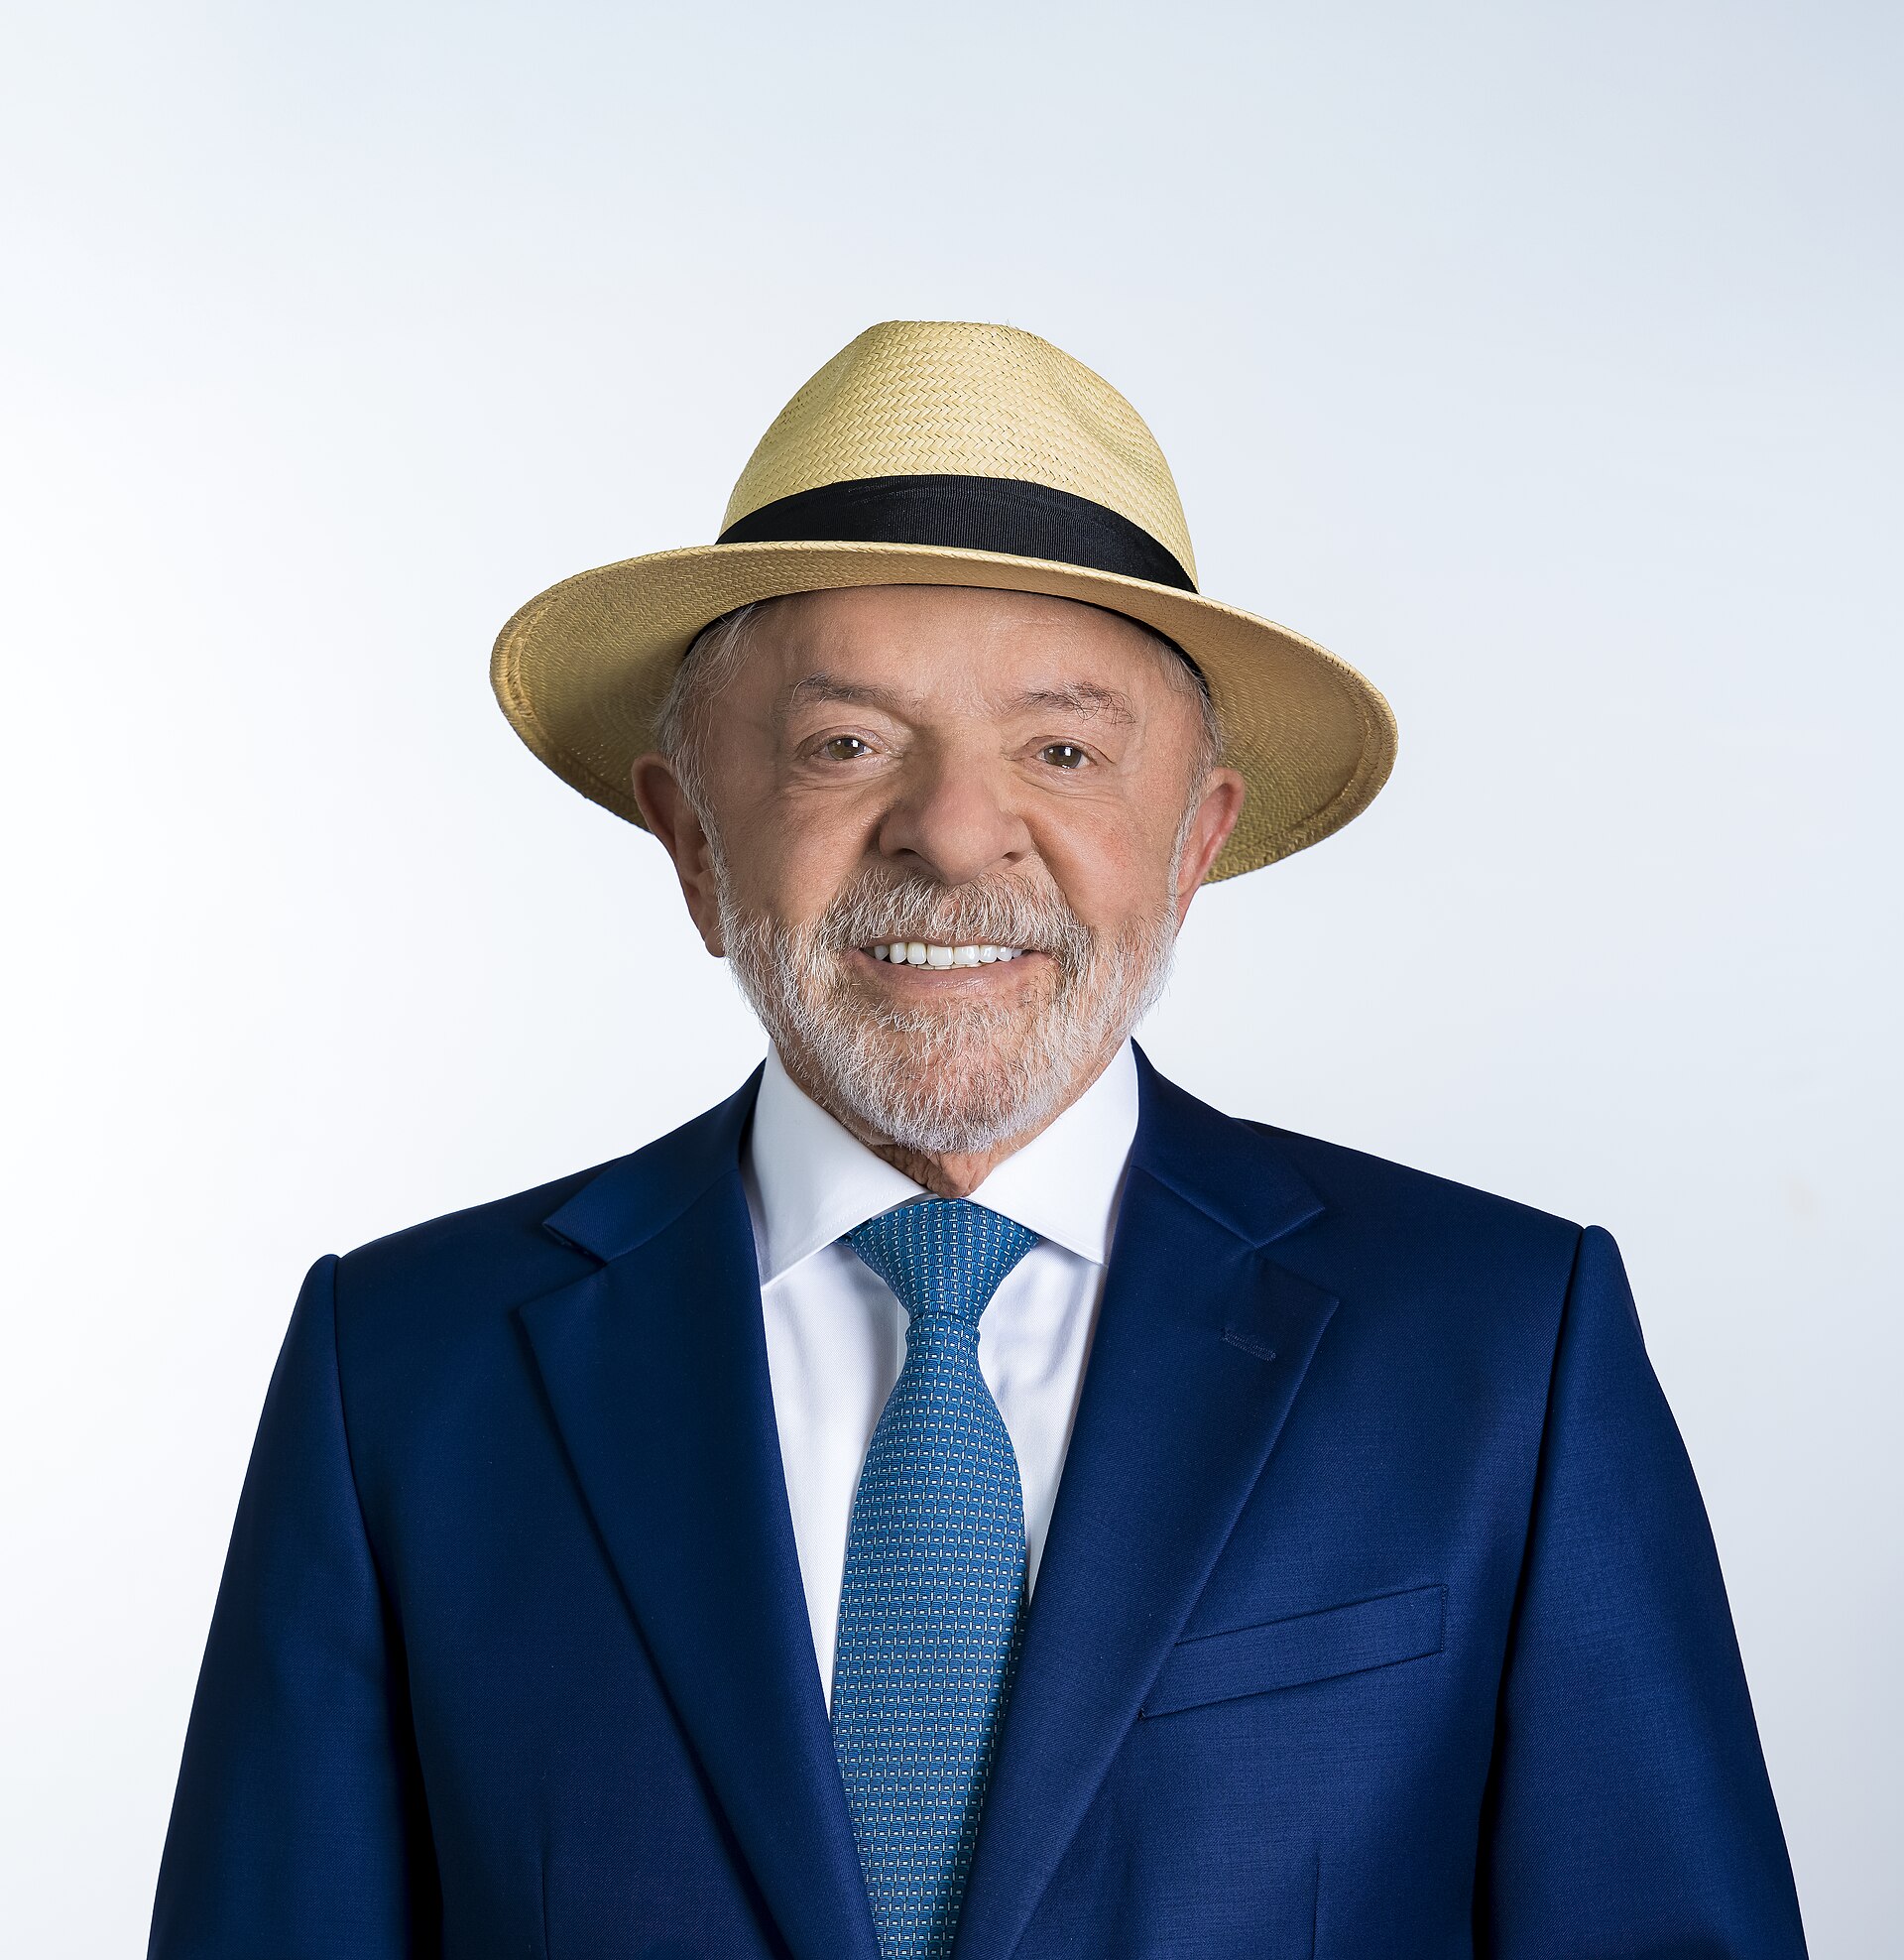
Luiz Inácio Lula da Silva won a fourth term as Brazil's president on Sunday, October 25, defeating Flávio Bolsonaro in the presidential runoff, according to the country's electoral court. Brazilian assets sold off sharply on the result, while U.S. stock futures and Treasurys (U.S. government bonds) were largely steady.
The electoral court's runoff announcement gave Flávio Bolsonaro (PL) 59,826,041 votes as the second-place finisher (Tribunal Superior Eleitoral). In the first round, Flávio Bolsonaro had taken 56,104,268 votes, while Lula received 53,876,617, or 45.16% of the valid vote (Tribunal Superior Eleitoral).
To my eye, the gap between the two rounds is the first clue that the outcome was not a runaway, which is why the market reaction is worth a closer look.
Investors had not positioned for this result. Reuters reported that investors expected Brazilian stocks and the currency to fall after Lula's reelection (Reuters). Reuters' morning briefing also noted that Lula's runoff victory caught prediction markets off guard (Reuters).
In practical terms, traders had bet on the other outcome, and prices had to move to reflect the real result.
The clearest read on the size of that move came from the New York-listed iShares MSCI Brazil exchange-traded fund, or ETF, a basket of shares that trades like a single stock. It showed a 24% decline in pre-market trading on Monday, October 26 (MarketWatch).
A 24% indicated move in a broad country fund is a large repricing for a single election. It falls directly on anyone holding Brazil exposure through a U.S.-listed vehicle.
The Wall Street Journal framed the day as a split screen. Its headline on the sell-off described Brazilian assets sliding while U.S. stock futures and Treasurys held steady (Wall Street Journal). Its earlier piece on the outcome had flagged the risk to the equity market and the real directly (Wall Street Journal). MarketWatch reported the Dow, S&P 500 and Nasdaq set for a steady start ahead of the Federal Reserve's October rate decision (MarketWatch).
CNBC described currency markets as subdued ahead of a pivotal central bank week, and noted that Treasury yields had fallen beforehand, which affects yield differentials between the U.S. and other markets (CNBC). A yield differential is the gap between the return on a government bond in one market and another.
In my view, that gap matters more than it first appears. When it narrows, the case for holding higher-yielding currencies such as the real weakens at the margin. Lower U.S. yields can therefore cushion a Brazilian sell-off or make it harder to fund one.
The broader context here is that this is a domestic political shock with a market channel, not a macro shock. U.S. futures did not follow Brazil lower, and the Treasury market did not treat the result as a reason to reprice U.S. rates. The open questions are the ones that matter for holders: whether the real and Brazilian equities stabilize once the initial repricing finishes, and whether the Fed's decision this week changes the yield backdrop that funds these flows.
For ordinary savers, the lesson is narrow. A country fund can fall sharply on a single result the market did not expect, and a U.S.-listed wrapper does not change the underlying exposure. For professionals, the question is how much of the move is repricing of a surprise and how much is a durable change in the policy outlook. The evidence supports the first reading for now. Anyone who claims to know the second is selling a forecast.


