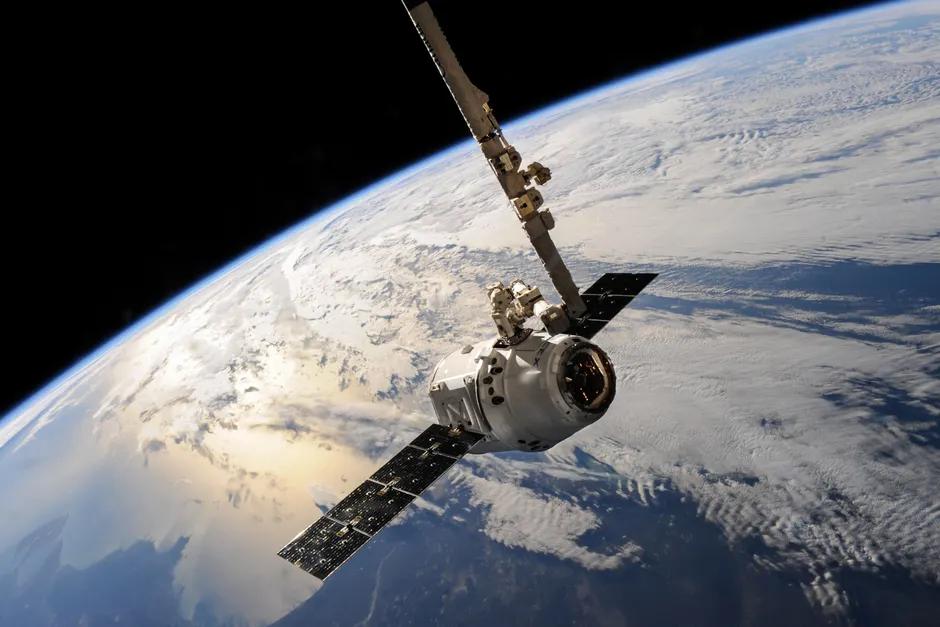
SpaceX Reportedly Eyes Boost Mobile as Starlink Moves Toward Wireless
SpaceX is looking to buy Boost Mobile from EchoStar, according to a Washington Post report cited by TechCrunch on November 2, 2026. The report presents the talks as a step toward making Starlink a larger presence in US wireless. The Verge reports that SpaceX aims to make Starlink a major mobile carrier.
Elon Musk spoke directly with EchoStar chairman Charlie Ergen in October about acquiring Boost Mobile. The talks are reported as an intent to buy, not a signed agreement.
Boost is a mobile virtual network operator (MVNO), which means it owns no towers. It leases capacity from AT&T and T-Mobile, so its subscribers connect through another carrier's radio access network (RAN), the cell sites and radios that link phones to the network. Boost handles the customer relationship, billing and branding. According to TechCrunch, EchoStar has about 7.5 million customers across Boost Mobile and GenMobile. EchoStar's corporate website separately states that Boost connects over 7 million Americans.
The reported deal follows an earlier attempt at a network arrangement. According to the same TechCrunch report, Musk approached AT&T, T-Mobile and Verizon about buying capacity on their networks, and all three rejected him. Each of those carriers has more than 100 million subscribers, which places them in a different category from Boost in terms of scale and infrastructure ownership.
Spectrum, the licensed radio frequencies that wireless service runs on, sits at the centre of the picture. Bloomberg reported on October 8, 2026 that SpaceX is acquiring low-band spectrum for mobile phone service from Grain Management LLC. Low-band signals travel long distances and penetrate buildings more readily than higher bands, which is why operators prize them for coverage. TechCrunch reports that SpaceX has bought $17 billion worth of wireless spectrum from EchoStar for cellular services.
The arrangement has been building for more than a year. In September 2025, EchoStar announced a spectrum sale and a commercial agreement with SpaceX, under which the two companies would enter into a long-term arrangement enabling EchoStar's Boost business. In November 2025, EchoStar entered into an amended definitive agreement with SpaceX to sell its unpaired AWS-3 licenses for approximately $2.6 billion. That transaction covers a separate block of spectrum from the $17 billion figure reported by TechCrunch.
EchoStar's stated plan for Boost is a cloud-native core network connected to AT&T cell sites and to SpaceX's future low Earth orbit (LEO) satellite network. In practical terms, Boost would keep relying on AT&T's radio sites for terrestrial coverage while moving the core, which handles authentication, session management and policy, onto a cloud-based architecture. That architecture would link to a satellite layer that is not yet operating at that scale.
The broader context here is a shift in who controls the stack. An MVNO is exposed to its host network's pricing, prioritisation and roaming terms. A carrier that holds its own spectrum, runs its own core and can route traffic over satellites has fewer of those dependencies. The incumbents' refusal to sell capacity to Musk, as TechCrunch reports it, makes spectrum and core ownership more important to any new entrant. Whether that becomes a durable competitor depends on terms and execution that are not yet public.
In my view, the questions that matter most for engineers and network planners are less about the headline price than about the interfaces. How Boost's cloud-native core hands off to AT&T's radio access network, how roaming and handover behave during the transition, and how a LEO layer would be integrated into a terrestrial service are open technical matters. They will determine whether the 7.5 million customers notice any change in service at all.
If the pieces fit, the combination could give a satellite operator a path into mobile service that does not depend entirely on rented capacity. For subscribers, the practical benefit would be coverage and pricing options beyond the three incumbents. For the industry, it would test whether a vertically integrated satellite and cellular operator can compete with carriers that have built their networks over decades. The deal is still an intent under negotiation, and the spectrum and satellite pieces are still being assembled.