The Yuan Hits a Four-Year High, but the Dollar Story Is Murkier

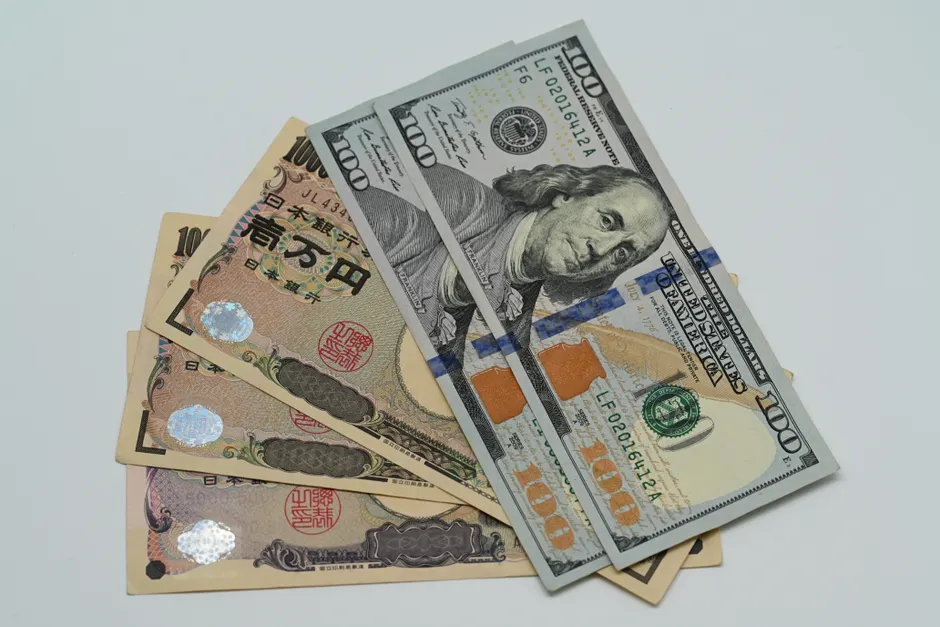
The Chinese yuan reached a four-year high against the dollar on October 20, 2026, according to a Yahoo Finance Singapore report on that day's Asian currency trading, which described the dollar as retreating in the same session.
The rest of that day's coverage does not agree on the dollar. A Wall Street Journal currencies report dated October 20 put the WSJ Dollar Index up 0.11% at 97.20. That index tracks the dollar against a basket of major currencies, so a rise means the dollar gained broadly. The same report's headline said the yen was consolidating but may be supported by a risk-off mood, meaning investors moving toward safer assets. A second WSJ headline from the same date said the pace of yuan gains against the dollar is likely to stay gradual.
In my view, a dollar that retreats in one report and firms in another is a single-session signal at best. I would not treat the October 20 move as a trend until the next few sessions confirm it.
The index level is the more useful reference point. The WSJ Dollar Index stood at 95.29 in a WSJ report from May 4, and at 97.15 after a 0.16% decline reported on October 6.
That puts the dollar firmer this autumn than in the spring, even as it oscillates within a narrow band. For forecasters, the gap matters. MUFG Research, in its July 3 Asia FX Outlook for 2H2026 (the second half of 2026), expected Asian currencies in aggregate to appreciate modestly against the dollar, supported by a softer dollar trend. Bloomberg reported on June 21 that analysts expected the Singapore dollar to strengthen against the greenback in the second half despite a hawkish Federal Reserve, meaning a central bank inclined to keep interest rates high.
The index has not moved in that direction. In my view, the currency-level outcomes have been mixed, and forecasts of a weaker dollar deserve the same scrutiny as any other consensus call. Analyst views are opinions, not measurements.
The weakest link in the region's recent data is the rupiah, Indonesia's currency. On October 16, it weakened 0.6% to 18,070 per dollar, its weakest level since late July, after index provider MSCI proposed consulting on a change affecting Indonesian markets.
The operative word is 'proposed'. A consultation is not a rule change, but index-linked passive flows, meaning money that automatically tracks an index, can shift foreign positioning in local markets well before any final decision. That is why currency traders reacted to the proposal itself.
India shows a different pattern. The rupee closed at 96.2925 per dollar in a session reported by Reuters on October 5, with the Reserve Bank of India intervening and most Asian currencies between 0.1% and 0.5% weaker that day. Intervention, meaning a central bank buying or selling its own currency, smooths the path but does not set the level. A rupee defended in one session can still drift lower in the next.
Oil runs through much of this. Reuters reported on September 17 that the dollar's allure and an oil surge were fanning bearish bets on emerging Asian currencies, including the yuan, won, Singapore dollar, rupiah, Taiwan dollar and rupee. A WSJ report dated October 12 said the Singapore dollar was consolidating against the dollar and could be weighed by higher oil prices. Reuters had flagged the same exposure in May, when it tracked Asian currencies since the start of the Iran war in late February 2026 and described them as flashing an oil shock alarm.
The mechanism is straightforward. For oil importers, a higher crude price widens the external gap, the difference between what a country pays abroad and what it earns, and raises demand for dollars. That is the channel through which energy markets reach the currency desk.
The yen has its own history of sharp moves. In an August 2 Reuters article on Japan's currency intervention, Reuters reported that the yen rose more than 1% against the dollar early in an Asian session on July 31, 2026, before paring some of those gains, after a surge of more than 3%.
Intervention episodes of that scale tend to reset positioning. In my view, the yen's current consolidation therefore tells us less about the dollar than the same move would in a quiet market.
For savers and borrowers, the practical question is whether the regional currency trend persists. A firmer yuan lowers the local-currency cost of dollar-priced imports for Chinese buyers, while a weaker rupiah raises the rupiah cost of dollar debt for Indonesian borrowers. Neither effect is large or immediate in the data reported so far.
The better test is whether the dollar holds its October range while oil stays elevated. If it does, forecasts of a softer dollar will look less credible, and the four-year yuan high will look more like a local event than a regional turn.