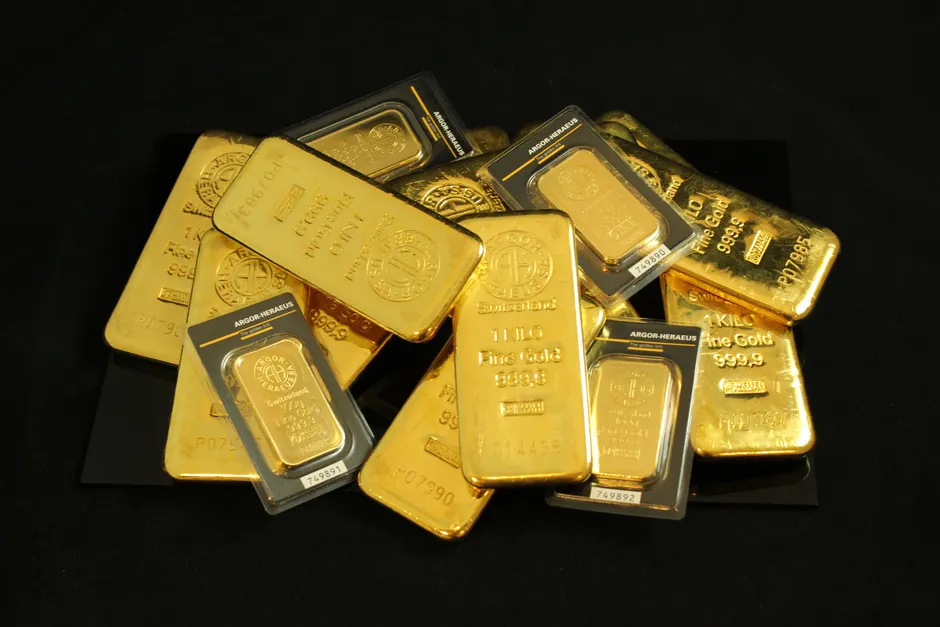
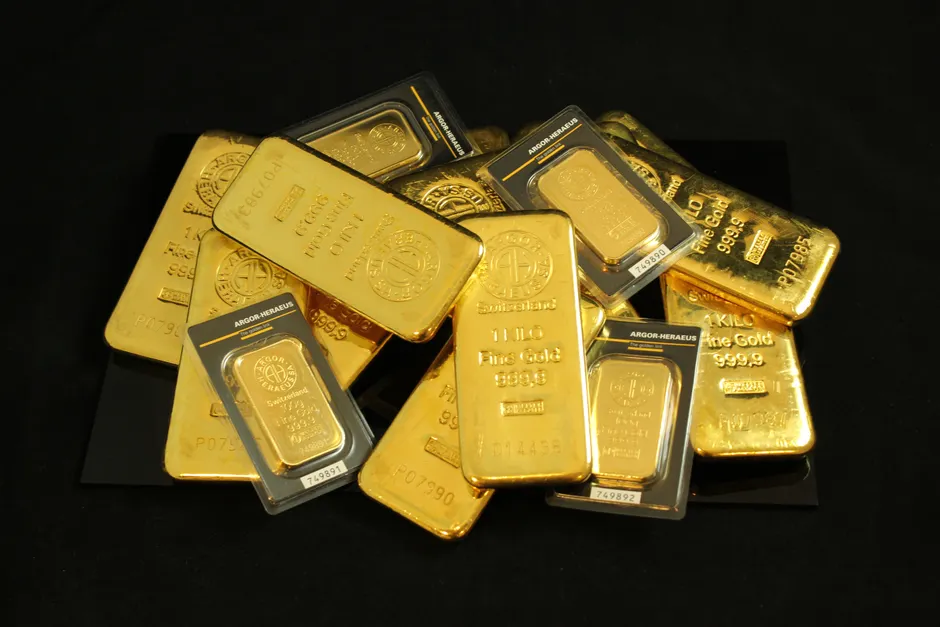
China's 21-Month Gold Buying Streak: Pace Picks Up

China's central bank bought gold for a 21st straight month in August 2026, taking reported reserves to 76.08 million fine troy ounces. Fine troy ounces are standard units for high-purity gold. The monthly increase was the largest since October 2023, according to official data reported by Reuters.
The People's Bank of China has been a leading buyer of gold since 2022, according to ANZ. The August 2026 disclosure shows buying continued. Pace quickened on the month. Stock rose.
Spot gold, the price for immediate delivery, rose 0.3% to $4,022.19 a troy ounce, according to a Wall Street Journal precious-metals report. That report tied the move to physical demand holding up prices, with potential China demand in focus. The WSJ framed the price action around that official-sector buying.
ANZ expects gold prices to rise to $4,800 in 2026, in research published in December 2025. The bank separately expects central-bank buying to stay around 950 tonnes, according to research published in June 2025. That figure is for central banks in total, not China alone. It points to continued net removal of metal from the amount freely available.
The broader context here is how flow and stock work together in gold prices. A 21-month run of net buying adds bit by bit to total reserves. But the steady flow matters for future prices, gold lending, and dealer stocks. Official buying tends to be less sensitive to price than buying through ETFs, funds that track gold on the stock market, or futures, contracts on future price. That difference shapes how traders read dips.
In my view, the question for prices is staying power versus speed. A long run without a break creates an expectation of a standing buyer, even when monthly amounts vary. The fastest pace since October 2023 adds information. It points to demand not yet full at higher spot levels. That favors tighter physical spreads, the gap between buying and selling prices, and smaller pullbacks after rallies.
Looking at what this means for reserves and market structure, central-bank buying near 950 tonnes leaves less metal for private buyers at any given price. The adjustment then runs through price, not amount, when the main buyer keeps buying. Swings around data releases can still come from leveraged paper bets. The clearing price for real metal reflects that official buying underneath.